Picture the inside of a bank: there is no pile of coins matching your account. The money is working, lent out, invested. What actually lies in a bank is invisible and matters more than gold. While the belief holds, the system runs — although there is not enough real money for everyone at once. That is why a crisis looks like an epidemic of fear.
Almost everything around you was made by somebody's hands: the bread, the road, the light in the room, the screen you are reading this on. We know the names of performers and bloggers but not of whoever brought water into the house. Their work becomes visible only when it suddenly is not there. A society is like a building.
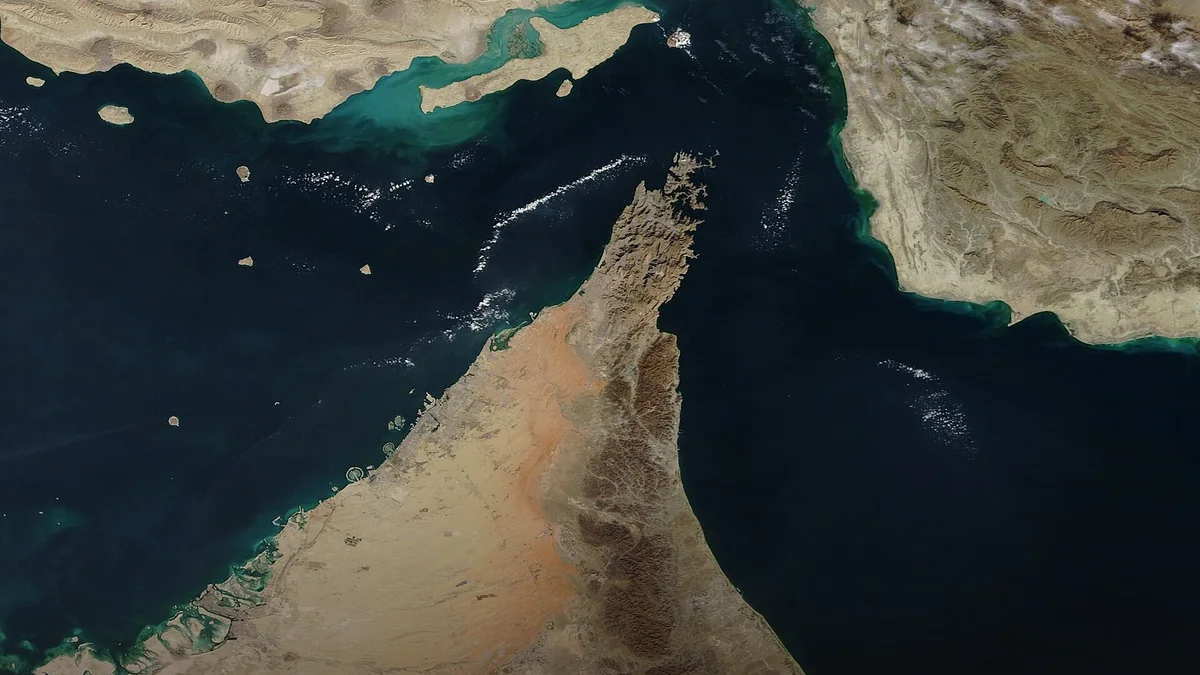
By mid-July a barrel of Brent costs about $78.82 — some 19% above the pre-war level, though early in the month the price had slipped back to seventy. The Strait of Hormuz, through which about 20% of the world's oil passes, is close to shut. Why for an exporting country this is both a gift to the budget and a trap.
Everything has a price in money, but money has a price in energy. The cost of bread, metal and the internet is ultimately the cost of the energy spent. There is a treacherous quantity too: how much energy must go in to get one unit out. When oil gushed, one unit invested returned a hundred. Today resources come harder.
Behind a handsome success story there is almost always a warehouse of failures nobody writes about. In a society that despises those who fail, people stop trying, and that costs more than any bankruptcy: we see the companies that went under, not the thousands of ideas never born for fear of shame.
Every wave of automation arrives under the same headline: the professions will disappear. More often something else happens — the profession changes its content. The cashier did not vanish when terminals arrived; they became an adviser. The accountant stopped adding columns and took up the meaning of the numbers.
Inflation is when the same money buys less tomorrow than it does today. There are usually two causes: more money in the economy than goods, or costs themselves rising. It is unfair by nature: property rises along with prices while wages and savings lose value. What actually helps, and what only sounds like it does.
A country can buy oil, weapons and technology, but a country that cannot feed itself is never truly independent. Oil can be replaced or postponed; food cannot — people eat every day. Hunger has toppled rulers more often than armies have. Why farming countries hold a card that money cannot buy.
Money looks like a thing — coins, notes, figures in an account. In substance it is an agreement: a banknote has value not in itself but because everyone around has agreed to take it in exchange for work. First people trusted gold, then states, now increasingly code. Why inflation destroys not notes but trust.
The news talks about corporations and mega-projects, and a cafe, a workshop or a one-person firm look like small change. They are what creates most of the jobs. There is a less obvious role too: a person with a business of their own depends less on a single employer. Many independent people are what makes a society steady.
Trade is often taken for a zero-sum game: if someone won, someone else lost. Economics showed the opposite two hundred years ago — exchange is addition, not confiscation. But an honest conversation does not end there: the gain is spread thinly across everyone, while the loss falls on a few, at once and hard.
Inflation is discussed in percentages as though it were the weather, but behind the average figure hides a very unequal distribution of pain. For a comfortable household it is holidays and gadgets that get dearer; for a poor one it is bread, medicine, transport and rent — the things that cannot be given up.


 Economy