

Subqueries and WITH: answer a complex question in steps
Break the savings-rate calculation into named, testable CTE stages.
Why this matters
Copying one long formula makes review difficult. Named intermediate steps reveal where a wrong total entered the calculation.
Image. CTEs are clear mixing bowls: prepare income and spending separately, inspect them, then combine them.
See the whole thing first
WITH monthly AS (
    SELECT c.kind, SUM(t.amount_tiyn) AS amount_tiyn
    FROM transactions AS t
    JOIN categories AS c ON c.id = t.category_id
    WHERE t.happened_on >= '2026-09-01' AND t.happened_on < '2026-10-01'
    GROUP BY c.kind
), totals AS (
    SELECT COALESCE(SUM(amount_tiyn) FILTER (WHERE kind='income'), 0) AS income,
           COALESCE(SUM(amount_tiyn) FILTER (WHERE kind='expense'), 0) AS expense
    FROM monthly
)
SELECT income / 100.0 AS income_kzt,
       expense / 100.0 AS expense_kzt,
       ROUND(100.0 * (income - expense) / NULLIF(income, 0), 1) AS saving_rate
FROM totals;
Explanation
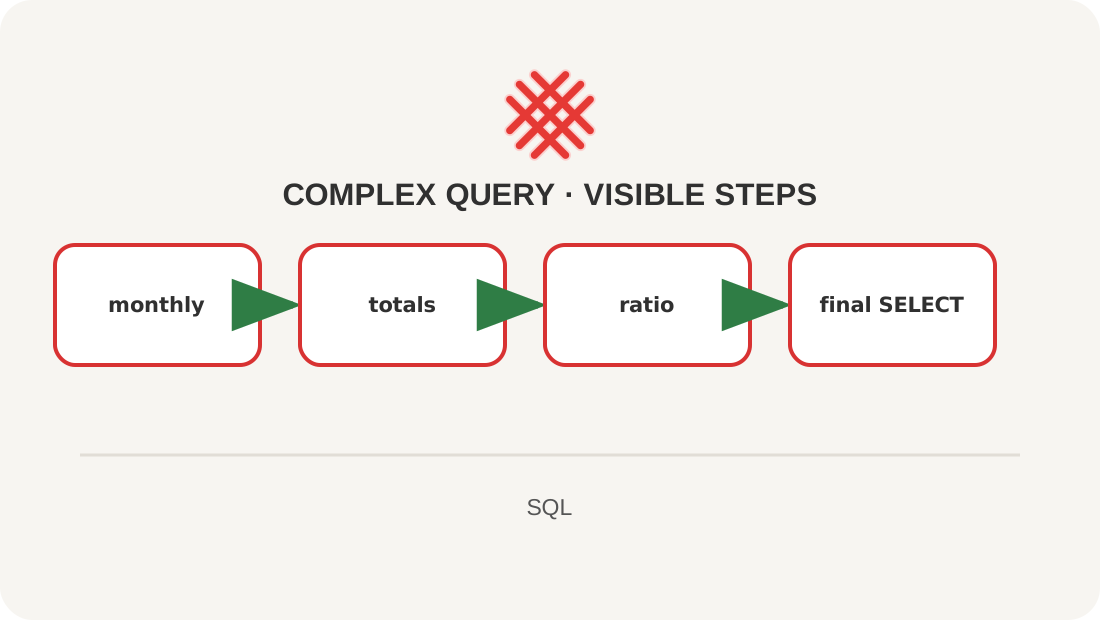
A CTE exists for one statement; it is not a stored table. Read several CTEs top-down as calculation stages. NULLIF(income,0) prevents a false percentage when income is zero. Correlated subqueries are not automatically slow; choose between them, joins, and pre-aggregation using clarity and the query plan.
Lesson map
Say it in your own words
- How does a CTE differ from a table?
- Why use NULLIF here?
- Why not declare every subquery slow?
Exercise
Add a CTE that returns spending as a percentage of income and NULL when income is absent.
Where this fits in the project
Named stages become the final report and let us test each calculation separately.
Answers
Show the answers
WITH totals AS (
    SELECT SUM(amount_tiyn) FILTER (WHERE kind='income') AS income,
           SUM(amount_tiyn) FILTER (WHERE kind='expense') AS expense
    FROM transactions JOIN categories ON categories.id=category_id
), ratio AS (
    SELECT 100.0 * expense / NULLIF(income, 0) AS expense_rate FROM totals
)
SELECT expense_rate FROM ratio;
Sources
If you have found a mistake or a typo in this article, tell us about it
Comments (0)
Log in to leave a comment →
No comments yet. Be the first.